As of 31 October 2026, Binance Research placed combined assets in US spot Bitcoin and Ethereum ETFs at about $111 billion. Over the same window, the average crypto hedge fund managed $132 million, and 91 percent of those funds were below $1 billion. The research, by Kim Lim and Jasper Jin and compiled by TechFlow, treats that gap as a distribution and verification problem rather than evidence that active managers lacked skill. Capital Connect figures and interviews through early November are presented as a platform snapshot, not a market-wide census.
Allocation intent versus where capital actually sat
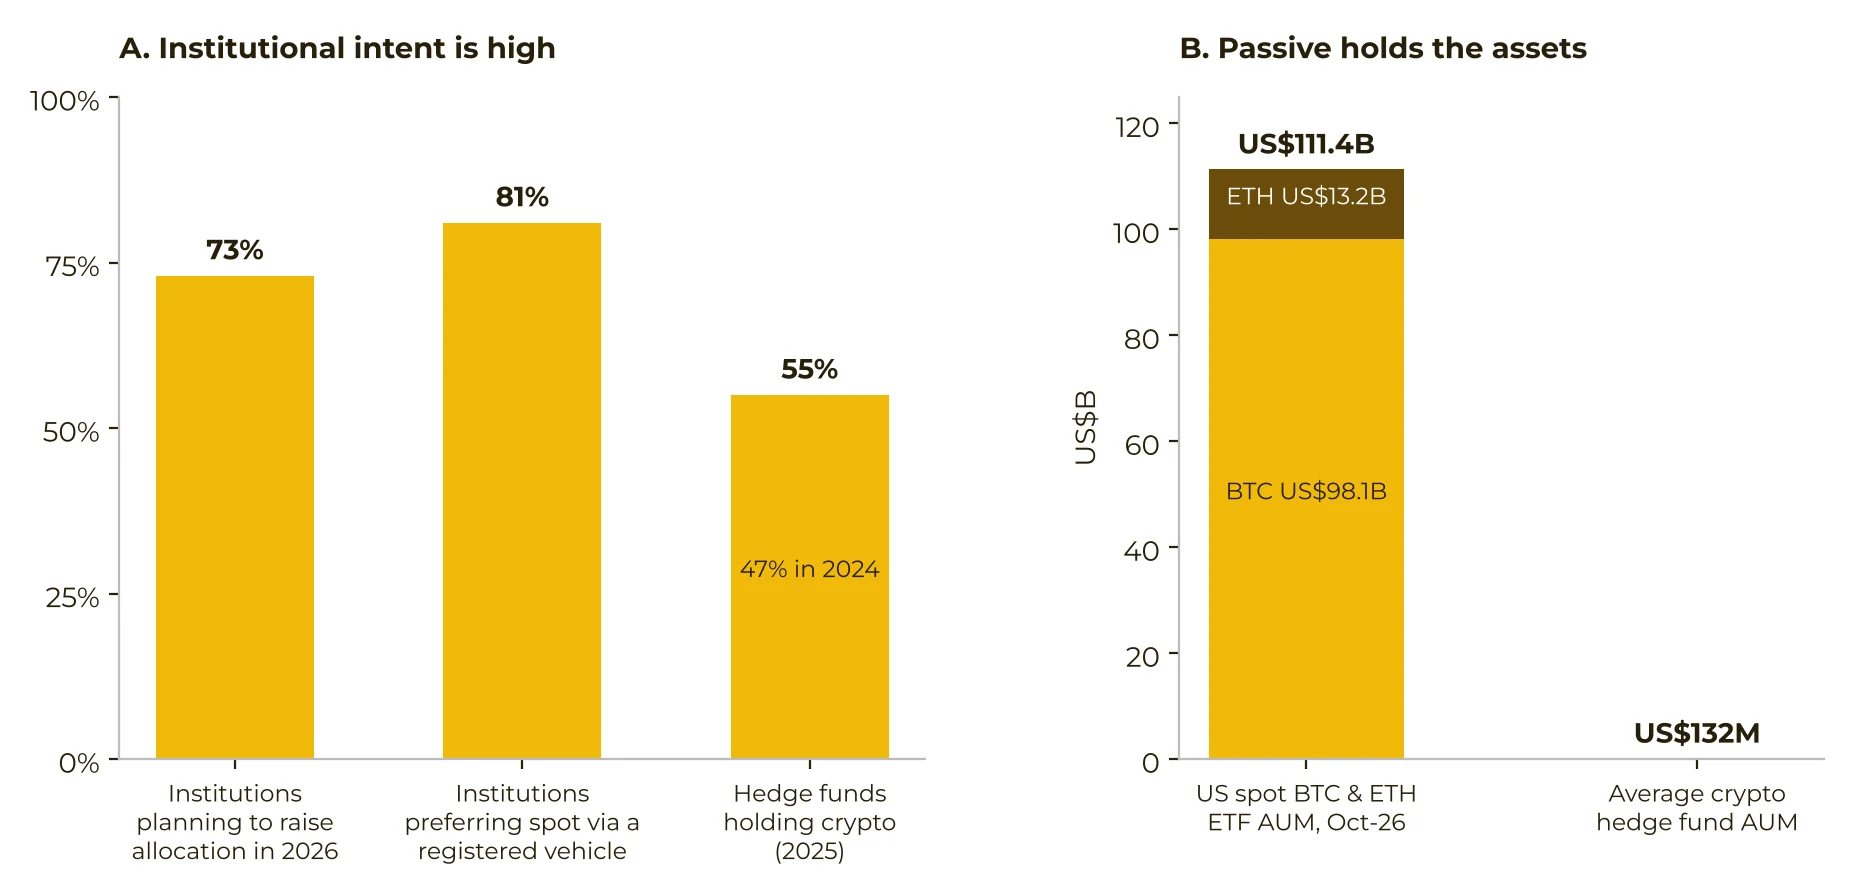
A March 2026 EY-Parthenon and Coinbase survey found that 73 percent of institutions planned to raise digital-asset allocations that year. An AIMA and PwC report put the share of traditional hedge funds holding crypto at 55 percent, up from 47 percent in 2024. Among institutions covered in the Binance Research synthesis, 81 percent preferred registered compliant products for spot exposure.
Position size stayed limited. More than half of traditional hedge funds that held crypto allocated less than 2 percent of total assets, while 60 percent planned to lift exposure above 2 percent within a year. The authors read the pattern as an infrastructure constraint: ETFs already bundled custody, audit, daily net-asset-value valuation, and reporting formats institutions already used. Active crypto strategies, in their view, had not matched that packaging. These survey results describe stated plans and current weights; they are not a measure of subsequent flows.
Discovery still ran through informal channels
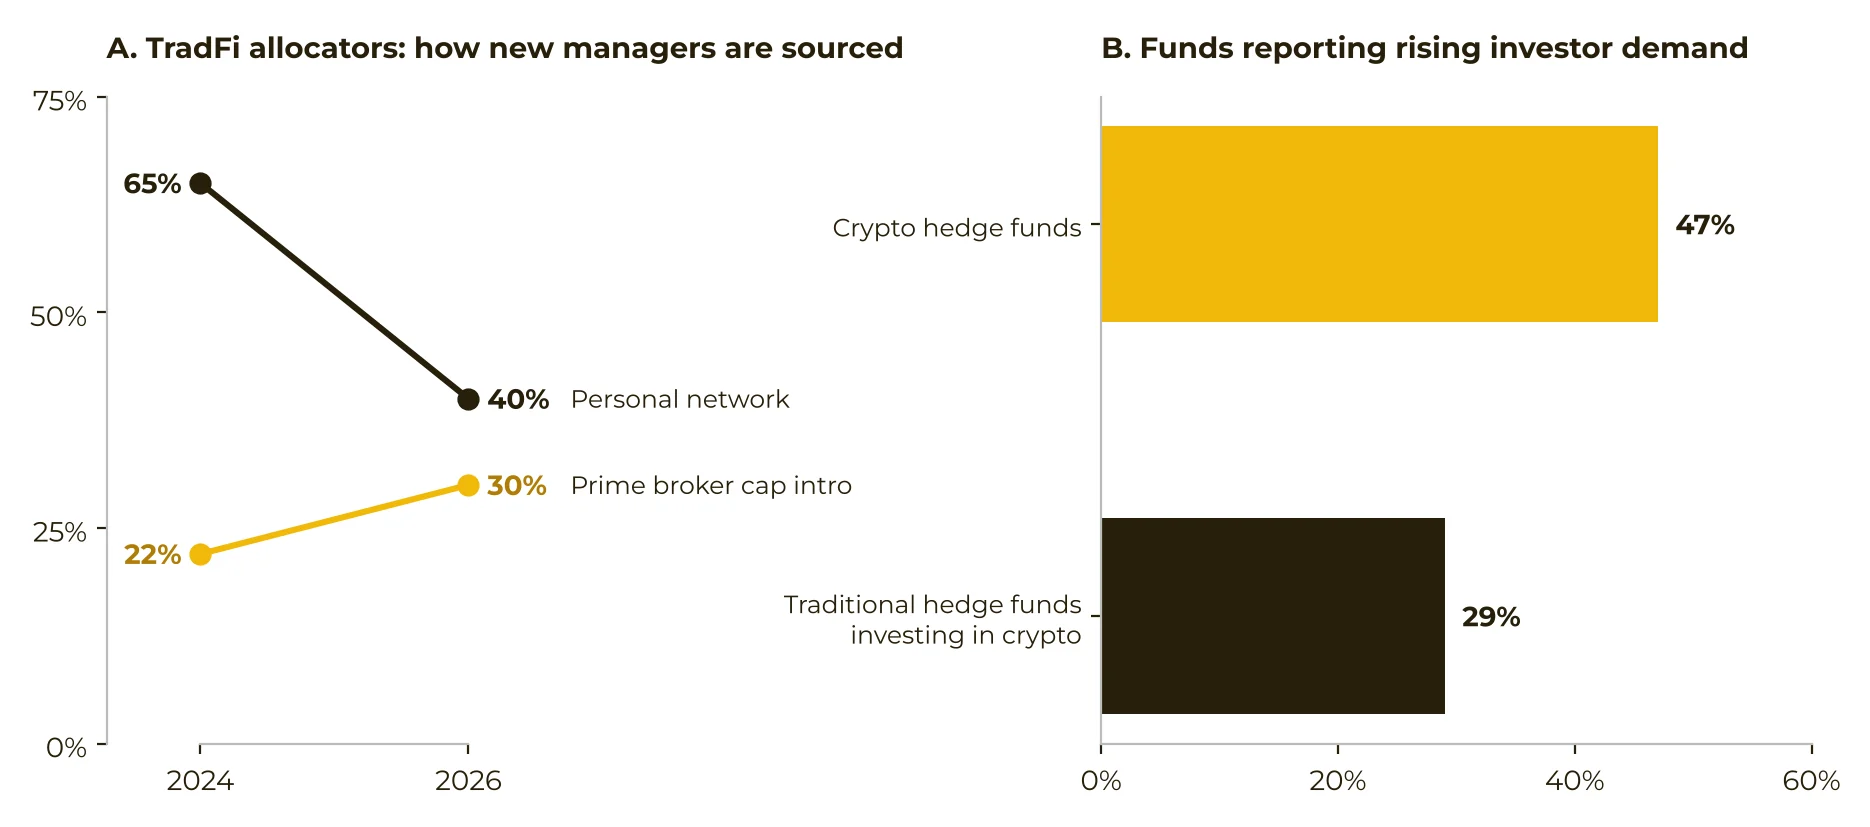
AIMA and Marex survey figures showed allocators’ reliance on personal networks falling from 65 percent in 2024 to 40 percent in 2026, while the share using prime-broker capital-introduction channels rose from 22 percent to 30 percent. The report said crypto allocation still depended heavily on Telegram groups, conferences, and referrals. Without a common performance disclosure and benchmark frame, investors could not compare managers on the same terms, and institutions struggled to check audited statements, custody arrangements, and service-provider credentials.
Demand signals were uneven. Forty-seven percent of crypto hedge funds said investor demand was rising, against 29 percent among traditional hedge funds involved in crypto. Family offices and high-net-worth individuals remained the main backers. Only one-fifth of crypto hedge funds listed pensions, foundations, or sovereign wealth funds as a primary investor type, up from one-ninth a year earlier.
Capital Connect: count and assets pointed different ways
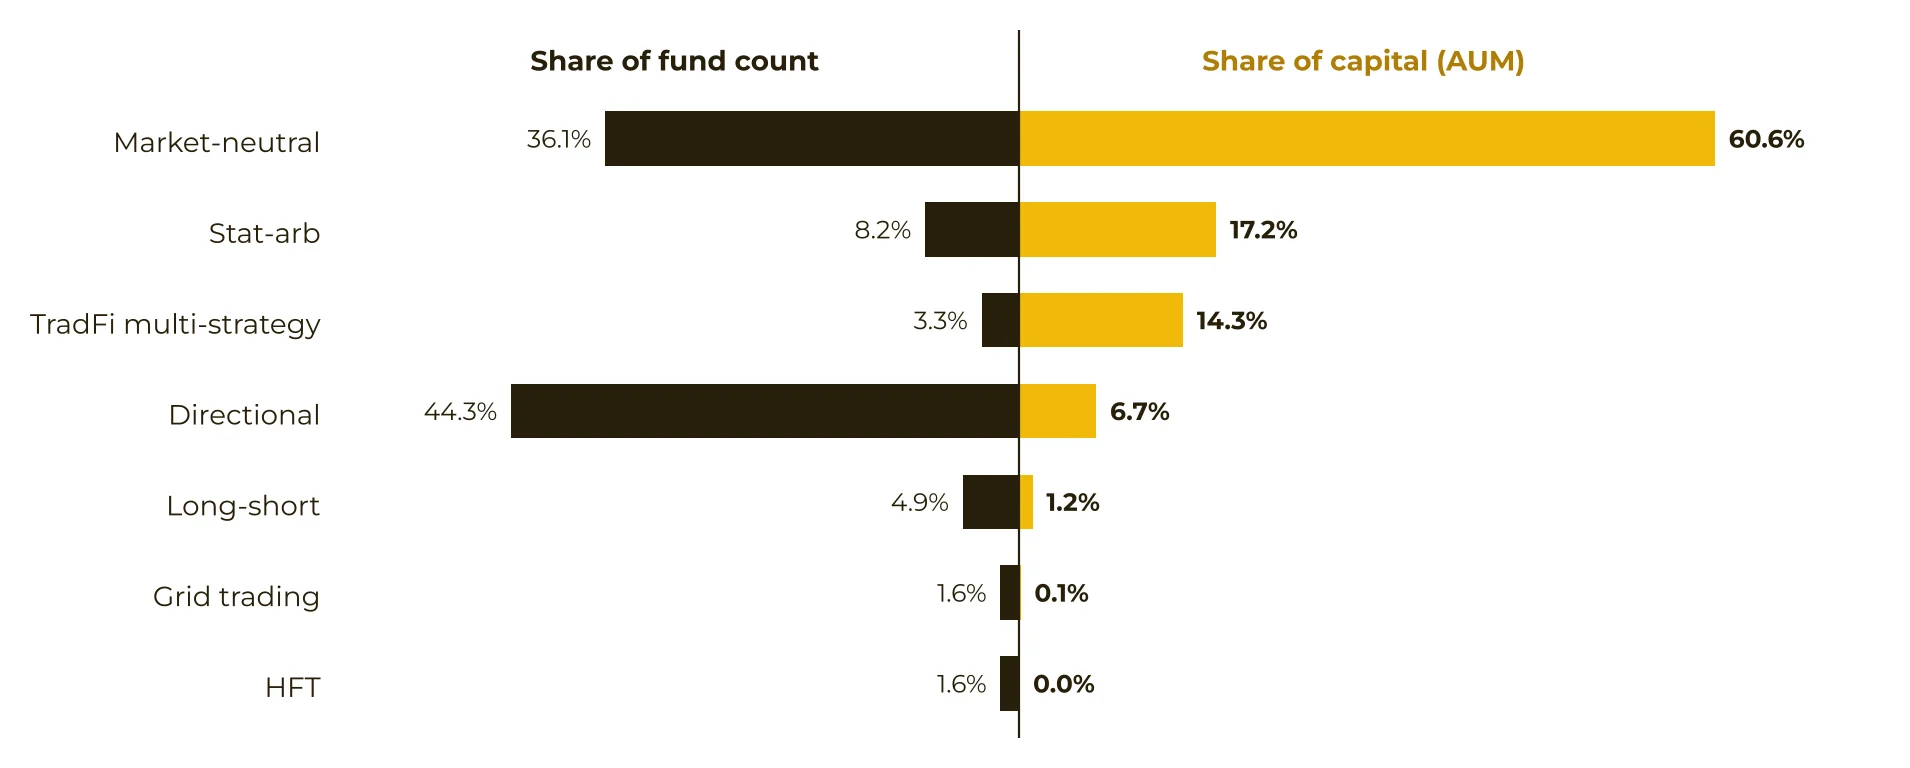
On Capital Connect, strategies are publicly disclosed and performance is scored on a shared standard. Through 31 October 2026, directional strategies were 44.3 percent of funds by count but only 6.7 percent of platform assets. Market-neutral, statistical-arbitrage, and traditional-finance multi-strategy funds together held 92.1 percent of assets under management; multi-strategy funds alone were 14.3 percent. Neutral strategies were under half the fund count. Their average ticket was about 11 times the directional average, which the authors treat as evidence of higher conviction when allocators did commit, not as a claim about future returns.
Participation moved with that split. Market-neutral investor participation rose for two consecutive months and was up 30 percent since May. Statistical-arbitrage participation more than doubled over the same span and stayed stable through October. Manager supply still leaned toward directional products while platform capital concentrated in hedged strategies. The report says the discovery layer revealed that preference; it did not create it.
Two mandate styles under the October price move
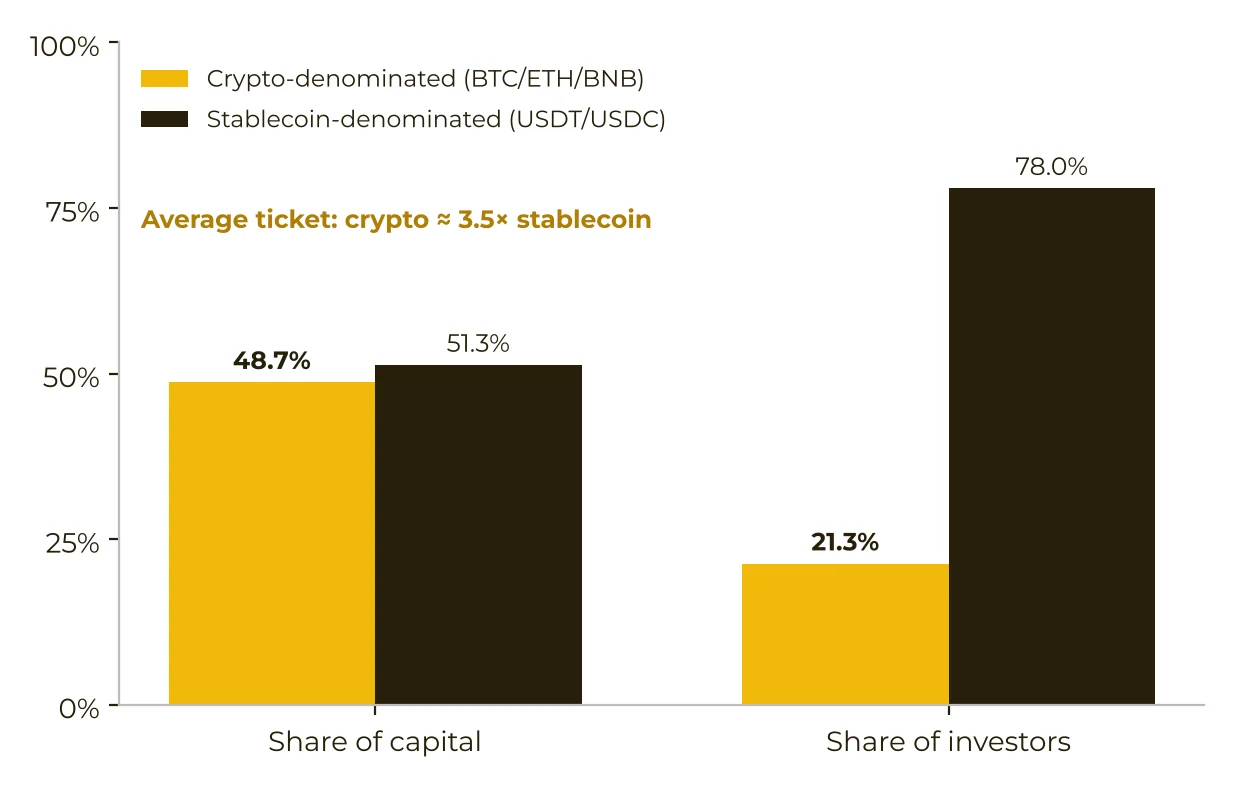
Funds denominated in BTC, ETH, or BNB held 48.7 percent of platform capital and about one-fifth of investors. Their average subscription was about 3.5 times that of stablecoin-denominated funds. Allocators kept the underlying coin exposure and outsourced the hedge. In October, coin-denominated holdings were described as stable; the dollar value of assets moved mainly with the bitcoin price.
Traditional-style multi-strategy funds remained third by assets at 14.3 percent. Their investor count fell 14 percent month on month in October, from 21 to 18. Binance Research called that selective screening as product structures became more familiar to traditional allocators, not a reversal of the broader pattern. Even where reported returns were steady, some investors stepped back for a period.
Directional participation recovered; dispersion stayed wide
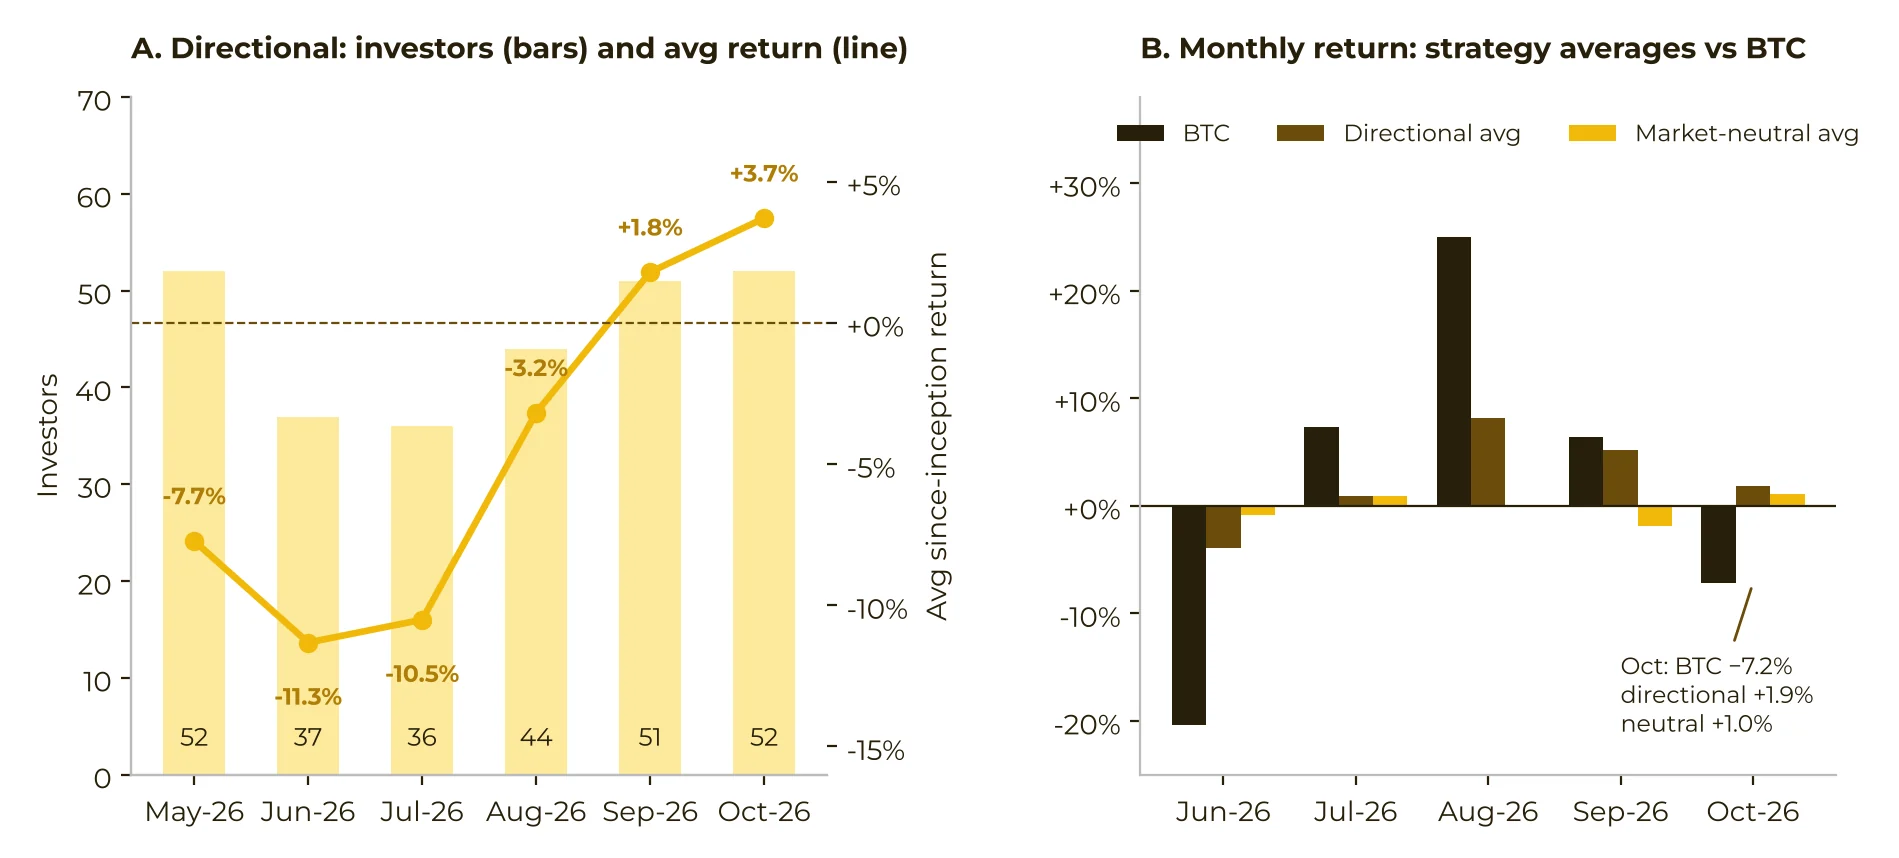
In the directional sample, investor count fell to 36 in July after returns bottomed in June, then recovered to 52 by October, matching the May level. Average since-inception return for directional funds improved from −11 percent in June to +3.7 percent in October. Those figures are simple averages of fund net asset values on the platform, not a cap-weighted index.
October was the first stress test of that rebound in the dataset. Bitcoin fell 7.2 percent that month. Directional funds still showed an average monthly return of +1.9 percent; market-neutral funds averaged +1.0 percent. Interviews described a repeated behavior: allocators tended to cut directional exposure during drawdowns and add it back after volatility and liquidity steadied. Price, fund-level returns, and stated allocator behavior are separate observations here; the report does not treat the positive monthly averages as proof that directional risk was compensated on a durable basis.
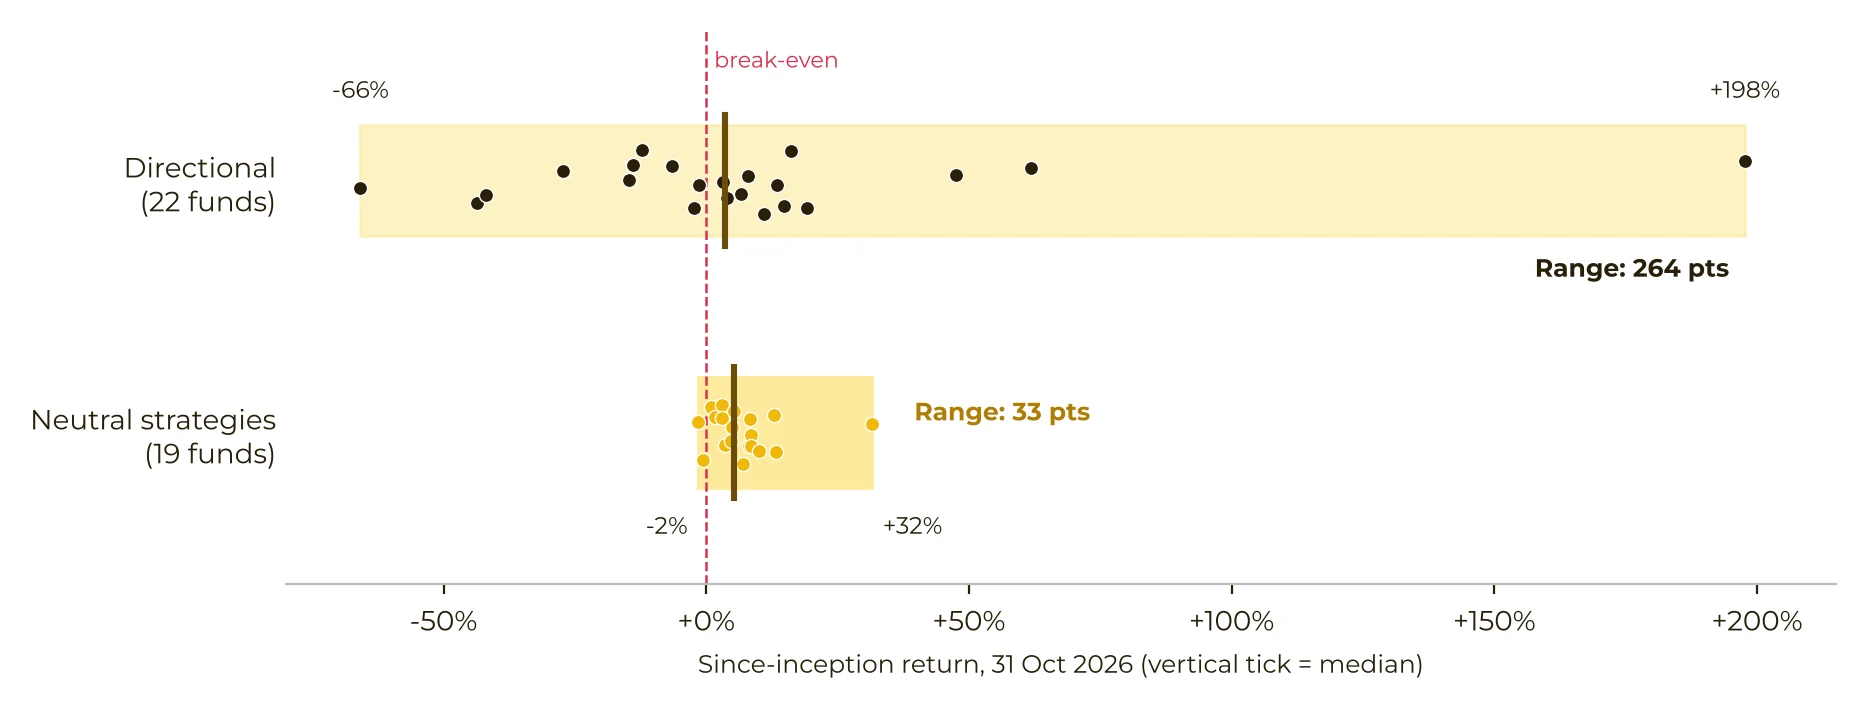
Dispersion remained large. The return gap between the best and worst directional funds was about eight times the range among neutral strategies. The directional median was near +4 percent, and only 55 percent of directional funds were positive, versus nine in ten neutral funds. Neutral figures combine market-neutral, statistical arbitrage, and traditional multi-strategy funds, and exclude dormant funds and funds below $1,000 in assets. The top quartile of directional funds averaged +69 percent since inception. Interviewed allocators said they would still pay for alpha at that level if drawdowns stayed controlled.
What allocators and managers said, 29 October–1 November 2026
Every interviewed allocator said verified exchange-internal data materially strengthened due diligence. Eighty percent ranked asset security above historical performance and institutional reputation, and they weighted drawdown control more than headline returns. Managers described the binding constraint as trust cost rather than insufficient returns: past results were hard to cross-check, and KYC, AML, and counterparty reviews slowed fundraising, so most capital still arrived through personal introductions. After listing, some managers said they could reach a wider set of investors, compliant institutions, and pools built from smaller tickets. Both sides framed verifiability as the condition that opened allocation, and operating infrastructure as what could widen the channel afterward.
The source states that the material is not a forecast, investment advice, or an offer to buy or sell any product, cryptocurrency, or strategy, and that views were current only as of the dates above and could change. Figures come from sources Binance Research regarded as reliable and are not presented as complete or error-free.
Original article, published 11 November 2026: PANews.